
Diversification and Correlation Regimes: Why Relationships Matter More Than Labels
Understand covariance, changing correlations, hidden factor concentrations and the limits of diversification during stress.
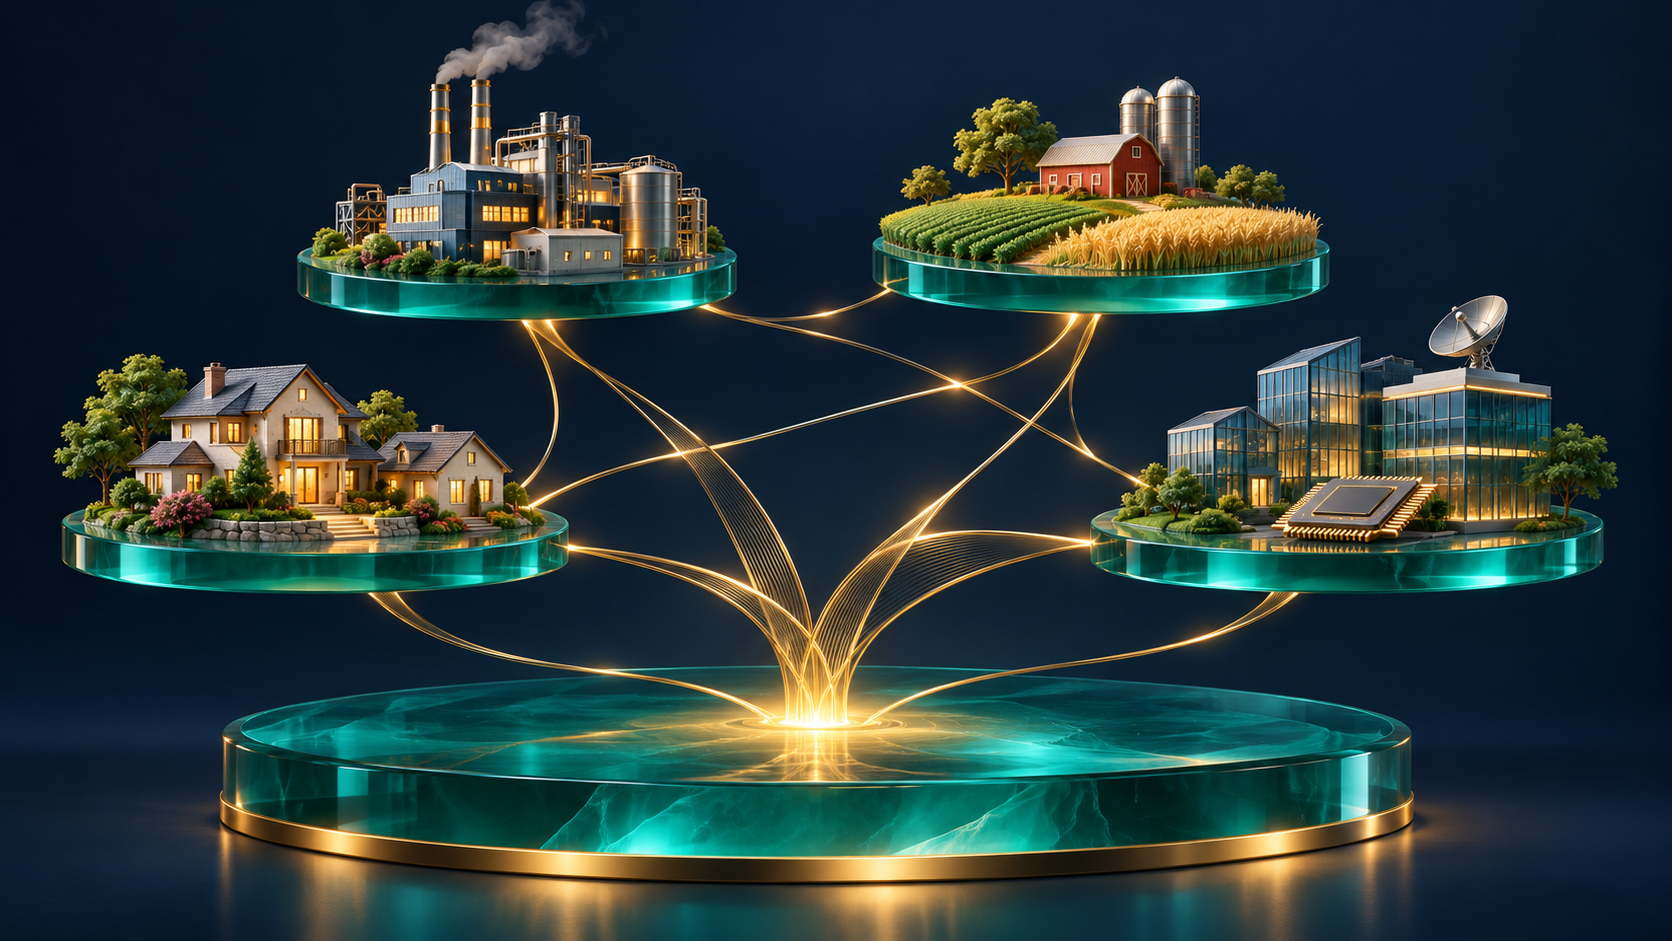
Many holdings can still share one economic dependence
Diversification is a property of combined exposures, not simply a count of securities. A portfolio can contain dozens of companies while depending heavily on the same customer group, financing condition, commodity or technological investment cycle. Different fund names can conceal overlapping holdings. Conversely, two instruments with similar labels may respond differently because their cash flows, currencies or maturities differ. The first question is therefore what could make several positions lose value together. This guide examines the statistical and economic meaning of diversification without prescribing an allocation. It treats correlation as evidence about a relationship under particular conditions, rather than as a permanent characteristic printed on an asset. The aim is to understand how apparently separate investments can become connected when the underlying environment changes.
Correlation standardizes co-movement; covariance keeps its scale
Correlation summarizes the direction and strength of a linear relationship between returns after adjusting for their individual variability. Covariance retains the scale of that variability. The distinction matters because two pairs of assets can have the same correlation but very different contributions to portfolio fluctuations if their volatilities differ. Zero correlation also does not prove independence: a nonlinear relationship can remain, and losses may cluster in particular states. A correlation estimate should identify the return definition, observation frequency, currency and sample period. Correlating price levels instead of properly constructed returns can produce a misleading impression of connection. A compact coefficient is useful, but it does not explain the economic mechanism or establish that one asset causes another to move.
Capital weights and risk contributions are not the same
Portfolio variability depends on position weights, each asset's variability and the relationships between them. Equal amounts of money do not necessarily produce equal amounts of risk. A more volatile holding can dominate fluctuations even when its capital weight looks modest. In a simplified hypothetical case, two equally weighted assets each have volatility of ten percent. If their correlation is one, their combined volatility remains ten percent. If correlation is zero, the standard two-asset variance calculation gives roughly seven percent. These are conditional mathematical illustrations, not forecasts or an allocation proposal. Changing volatility or weights changes the result. Expected returns, financing costs, taxes and the possibility of large losses are separate questions that this simplified variance example does not answer.
Look through wrappers to find shared risk factors
A fund wrapper does not erase the economics of what it holds. Several products can own the same large companies, lend to similar borrowers or depend on the same interest-rate exposure. Geographic labels can be equally incomplete: a domestically listed company may earn revenue abroad, while a foreign company may depend on domestic customers. Currency denomination is not identical to economic currency exposure. Understanding these connections requires examining underlying holdings and business activities rather than counting product categories. A useful conceptual map separates issuer-specific events from broad influences such as growth, inflation, financing conditions and commodity costs. Adding another security that responds to the same influence may increase the appearance of variety more than the independence of the portfolio's outcomes.
The same assets can react differently to different shocks
The relationship between equities and government bonds illustrates why economic context matters. A deterioration in demand may weaken corporate earnings expectations while reducing expected interest rates, creating conditions in which high-quality bond prices rise as equities fall. An inflationary supply shock can pressure earnings and raise required yields at the same time, allowing both asset prices to decline. These are possible transmission channels, not universal laws. Starting valuations, policy credibility, maturity and credit quality can alter the outcome. A correlation observed during one dominant shock cannot automatically be carried into another environment. Regime analysis asks which forces are driving returns and how their importance changes. It does not require pretending that a new regime can be identified precisely and immediately.
Average correlation can conceal shared large losses
A relationship measured across all observations may look reassuring while describing stressful episodes poorly. Tail dependence concerns how outcomes behave together in the extreme parts of their distributions. Two assets can show moderate average correlation yet suffer large losses in the same adverse scenarios. Forced sales, common lenders and margin demands can connect positions that normally appear separate. It is also inaccurate to say that every correlation always becomes one in a crisis. The result depends on the assets, shock, horizon and measurement method. The practical analytical lesson is narrower: average co-movement alone does not describe the joint downside. Historical stress periods and explicitly hypothetical scenarios provide additional perspectives, but neither can exhaust every possible future combination of events.
A correlation estimate inherits the weaknesses of its data
Short samples can react quickly but produce unstable estimates; long samples can appear stable while averaging across different environments. Daily and monthly returns need not reveal the same relationship. Non-synchronous trading, stale prices and appraisal-based valuations can make some assets appear less connected than their underlying economics suggest. A currency conversion can also change the measured return pattern. These issues are not solved by displaying more decimal places. An informative comparison states how observations were aligned and what was excluded. It also separates an estimated historical relationship from an assumed future one. Sensitivity to alternative windows or frequencies can reveal fragility in a conclusion, without implying that one particular historical sample is a perfect representation of the future.
Diversified valuations do not guarantee diversified liquidity
A portfolio can be diversified in its expected returns yet depend on one funding channel or a narrow set of assets to meet near-term cash calls. Liquidity is about the ability to deliver resources when required, not only the final value of holdings. Margin increases can coincide with falling prices and wider transaction costs. An asset that ultimately retains value may still be difficult to sell quickly without a concession. Counterparty, custodian and operational dependencies can create additional concentrations that a return-correlation matrix does not display. For institutions, asset and liability currencies and maturities also matter. This broader view explains why diversification of market exposure should not be confused with assured access to cash under stressed conditions.
Scenario analysis exposes the assumptions behind apparent balance
Consider a hypothetical collection of exporters, banks, property companies and government bonds. The sector labels look varied. A sharp domestic rate increase could nevertheless affect credit demand, property financing, discount rates and currency translation across several holdings simultaneously. A different scenario, such as weaker foreign demand with lower domestic rates, might produce a different pattern. Neither example forecasts an event or specifies a preferred allocation. Their purpose is to test the narrative behind the labels. A coherent scenario states the initial shock, the transmission channels and the assumptions about policy and financing. It also distinguishes valuation changes from cash requirements. Contrasting scenarios is more informative than declaring a portfolio diversified because one historical average correlation is low.
Treat diversification as a changing relationship
Diversification can reduce the influence of individual failures and some patterns of joint fluctuation, but it cannot make all economic uncertainty disappear. Its meaning changes with weights, holdings, market structure and the investor's obligations. A careful explanation therefore reports both what has been diversified and what remains shared. It distinguishes issuer variety from factor variety, ordinary variability from extreme losses, and valuation resilience from funding resilience. It also acknowledges estimation error instead of selecting only the period that supports a preferred conclusion. The central insight is that portfolio risk comes from interactions. Understanding those interactions requires combining statistics with a credible account of cash flows and economic incentives, while remaining explicit about the conditions under which the account might stop working.
Sources & further reading
Primary institutional sources underpin this educational guide. Follow the links for the original definitions, methods and research. Hypothetical examples in the text are explanatory, not current quotes or forecasts.
- SEC: Asset Allocation and Diversification ↗
- FINRA: Concentration Risk ↗
- CFA Institute: Portfolio Risk and Return ↗
- CFA Institute: Portfolio Mathematics ↗
- CFA Institute: Statistical Measures of Asset Returns ↗
- BIS: The Correlation of Equity and Bond Returns ↗
- IMF: Stock-Bond Diversification and Market Selloffs ↗
- Banque de France: When Diversification Fades ↗
- CFA Institute: When Diversification Fails ↗
- BIS: Liquidity Risk Management and Supervision ↗
- BIS: Liquidity Preparedness for Margin and Collateral Calls ↗
- ECB: Financial Stability Review November 2022 ↗
Explore the data and markets
Continue your research
All guides →
Productivity, Wages and Living Standards: How Economic Gains Reach Households
A practical guide to output per hour, capital deepening, multifactor productivity, pay distribution and the limits of economic averages.

Demographics and Ageing Economies: Work, Pensions, Care and Capital
How population age structures interact with employment, migration, pension systems and investment—and why demographic projections are not economic destiny.
Market Liquidity and Order Books: What a Quote Can—and Cannot—Tell You
Understand spreads, depth, execution trade-offs and liquidity stress through clear examples and primary institutional sources.