
Silver: how industrial demand and monetary demand interact
Understand silver through electronics, solar intensity, jewellery, investment flows, by-product mining, recycling and inventory mechanics.
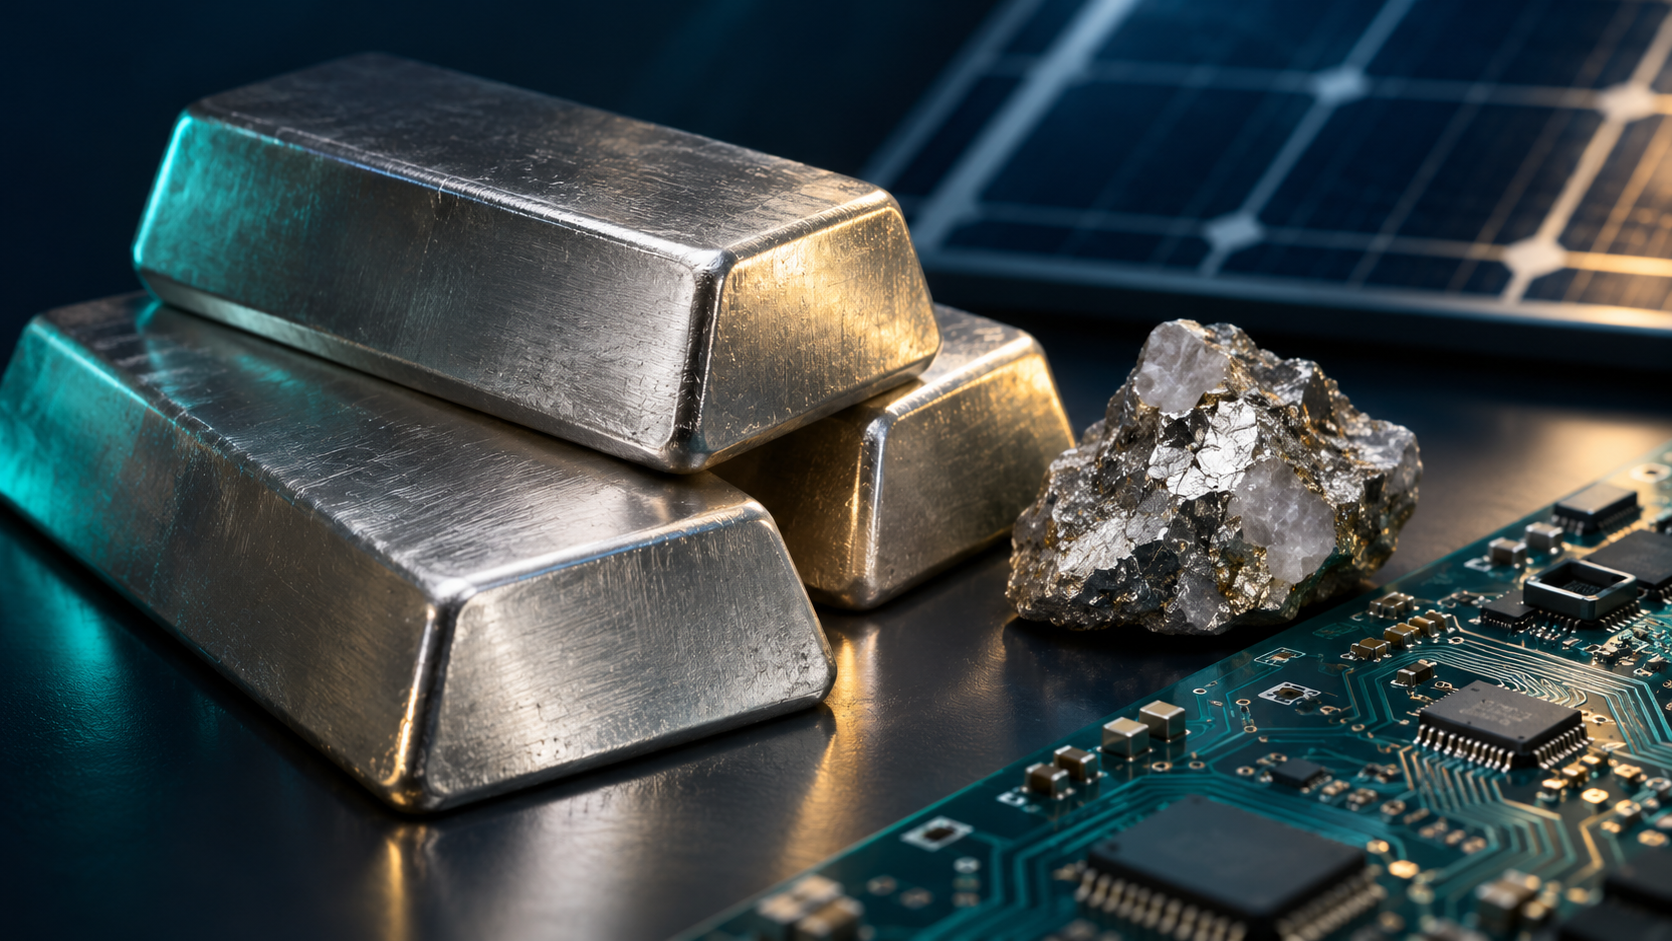
One metal, two different demand systems
Silver connects two worlds that do not always move together. Manufacturers purchase it to obtain useful physical properties, while investors acquire exposure because they expect a financial return or want a tangible store of value. A stronger manufacturing cycle can support fabrication even when investors reduce holdings. Conversely, concern about currencies can stimulate investment demand while industrial orders weaken. Treating silver as simply a cheaper version of gold hides this tension. Its monetary history matters, but its exposure to production decisions also matters. A useful analysis begins by separating industrial fabrication, jewellery and silverware, physical investment, and changes in financial holdings. Those categories have different buyers, time horizons and sensitivities. Their combination explains why an attractive long-term technology story can coexist with disappointing short-term price performance, or why a sudden financial rally can outrun changes in factory consumption.
Electrical performance creates industrial value
Silver's conductivity helps explain its use in electrical contacts, conductive inks and electronic components. The economic question is not merely whether a product contains silver, but how much silver is needed to deliver a specified level of reliability. A tiny contact can be essential to a much more expensive device. That makes performance and qualification requirements important alongside the metal price. Manufacturers cannot necessarily change a material immediately without testing durability, temperature behaviour and compatibility with production lines. Nevertheless, a valuable application is not proof that demand is permanently insensitive to price. Engineers can redesign components, reduce material thickness or qualify alternatives over time. For an analyst, shipment growth and silver intensity should therefore be investigated separately. Counting more devices is useful, but translating that count into metal demand requires evidence about the design and silver content of those devices.
Solar growth and silver intensity can diverge
Photovoltaic manufacturing is a clear example of the distinction between adoption and material intensity. More solar installations do not automatically imply an equal percentage increase in silver consumption. Cell technology, conductive paste formulation, production yield and substitution all affect the amount used per unit of output. Consider an explicitly hypothetical calculation: if manufacturing output rises by 20% while silver use per unit falls by 25%, total silver consumption becomes 1.20 multiplied by 0.75, or 90% of its starting level. Demand falls despite rapid production growth. This does not predict any actual year's result; it illustrates why installation headlines alone are insufficient. Timing adds another complication. Material can be purchased before modules are manufactured, and modules can remain in inventory before installation. Research should distinguish cell production, module shipments, installation and metal procurement rather than treating them as simultaneous measures.
Jewellery combines material cost and consumer behaviour
Jewellery and silverware demand cannot be understood from industrial production alone. Household purchasing power, cultural gifting practices, fashion, local exchange rates and retail margins influence purchases. A global dollar quotation can be stable while the local-currency cost rises sharply. Finished jewellery also contains design, labour, distribution and brand value, so its retail price is not a simple multiple of bullion content. This matters when comparing fabrication figures with consumer spending. More spending can reflect higher prices rather than more ounces. The reverse is also possible when consumers choose lighter products or different purities. Recycling introduces another distinction: selling an old object releases metal even when new jewellery purchases weaken. A credible demand discussion therefore identifies whether a series measures fabrication, retail turnover, exports or net consumption. Each answers a different question about the same broad consumer market.
Investment demand depends on the instrument
A coin, a wholesale bar, a futures position and shares in a mining company provide different economic exposures. Retail bullion purchases involve fabrication premiums, dealer spreads and storage arrangements. Exchange-traded products require inspection of their legal structure, expenses and underlying assets. Mining shares add operating, financing and management risks that do not disappear when silver prices rise. Futures introduce contract size, margin, expiry and settlement obligations. An investor can gain or lose exposure without immediately ordering newly mined metal, so financial activity should not be translated mechanically into physical consumption. For research purposes, identify the instrument before describing flows. Changes in holdings, gross trading volume and net new purchases are not interchangeable. A high-volume session may reflect repeated transfers of existing positions rather than an equivalent addition to metal held outside the market by long-term owners.
By-product supply weakens simple price-response assumptions
Part of silver production comes from mines whose economics depend substantially on other metals. A copper, lead, zinc or gold operation can produce silver as a by-product or co-product. Its decision to expand is therefore not governed by the silver quotation alone. Ore grades, recovery rates, permits, capital budgets and the profitability of the main product all influence output. Rising silver prices might improve revenues without making a new project immediately feasible. Equally, strong production of a host metal can bring additional silver into the market even when silver's own price signal is weak. This creates a supply response with delays and cross-market dependencies. Reading a silver balance consequently requires more than counting dedicated silver mines. Company guidance should be examined for ore throughput, grade and metallurgical recovery, while distinguishing mine production from refined supply that may also incorporate recycled material.
Recycling depends on collection and concentration
Silver does not become equally recoverable merely because it exists in a discarded product. A substantial bar is easier to identify, collect and refine than tiny quantities dispersed across many low-value devices. Collection networks, transport, processing technology and the price paid for recovered material all shape recycling economics. Industrial scrap can be relatively concentrated and generated regularly, whereas end-of-life consumer products may remain in drawers or mixed waste for years. Higher prices can encourage recovery, but they cannot instantly create collection systems or remove technical constraints. It is also important to distinguish new manufacturing scrap from old products reaching the end of their useful lives. These streams respond to different drivers. A rise in recycled supply may reflect stronger factory activity, greater household selling, or improved recovery infrastructure; those explanations have very different implications for future availability.
A market deficit is an accounting result, not a price timetable
Published supply-and-demand balances compare defined flows over a period. If measured demand exceeds measured new supply and recycling, existing stocks or other balancing items must bridge the gap under that accounting framework. This does not specify the date of a price increase, nor does it prove that every form of metal is unavailable. Inventories differ by location, ownership, purity, bar format and willingness to sell. Metal held by a long-term owner is not automatically offered at the prevailing quotation. Conversely, a shift in investor preferences can release stocks rapidly. Methodology matters because some reports classify investment flows differently. Before comparing deficit estimates, align their definitions and revisions. An analytical note should state what is counted, what remains estimated, and which inventory evidence supports the interpretation. A single annual balance cannot describe every local physical premium or delivery constraint.
Volatility reflects competing narratives and financial mechanics
Silver prices can react simultaneously to expectations about growth, interest rates, currencies and industrial demand. These influences can reinforce or offset one another. A weaker growth outlook may reduce expected fabrication while also changing expectations for monetary policy. Leveraged positions, margin requirements and the need for liquidity can then amplify a move without indicating an equivalent change in physical use. Comparing silver with gold can be informative, but a price ratio is a relative valuation observation rather than a physical law. There is no universal ratio to which prices must return on schedule. Analysts should compare returns over matched dates and currencies, then examine the economic differences behind them. The practical question is which driver changed and whether the evidence comes from consumption, available inventories, financing conditions or position adjustment, rather than whether a familiar narrative sounds persuasive.
Build a research note that separates evidence from inference
Start a silver research note with the period, unit and market being studied. Record whether quantities are fine metal content, gross product weight or financial notional exposure. Next, divide demand into end uses and separate shipment growth from material intensity. On supply, distinguish dedicated mines, by-product operations and recycling. Then review inventories and delivery standards without assuming that all reported stocks are immediately available. Financial analysis should identify the exact instrument, quotation currency and costs relevant to the comparison. Finally, write competing scenarios rather than a single predetermined outcome. One scenario may combine manufacturing expansion with rapid material savings; another may involve weaker production but stronger investment flows. State what new evidence would distinguish them. This framework turns a broad commodity story into a testable set of questions, while keeping explanations separate from price targets and personalized investment decisions.
Test a scenario. Explore the market.
Hypothetical inputs for learning. Change the assumptions to see the arithmetic; these are not current market values or forecasts.
Same period for both inputs. Before taxes and fees. Formula: (1 + return) ÷ (1 + inflation) − 1. Methodology ↗
Input limits: returns, inflation and currency changes −99% to 1,000%; duration 0–30; yield changes −200 to 200 basis points.
Open an interactive market chart
Market context, not a direct measure of every subject in this article. Provider data may be delayed or unavailable. Check the instrument, quote currency and timestamp.
Open the full market workspace →Sources & further reading
Primary institutional sources underpin this educational guide. Follow the links for the original definitions, methods and research. Hypothetical examples in the text are explanatory, not current quotes or forecasts.
- USGS: Silver statistics and information ↗
- USGS: Mineral Commodity Summaries 2025 ↗
- Silver Institute: Supply and demand ↗
- Silver Institute: Silver in electronics ↗
- Silver Institute: Silver price and investment ↗
- Silver Institute: World Silver Survey 2026 ↗
- LBMA: London Good Delivery, gold and silver ↗
- CME: Silver futures contract specifications ↗
- Silver Institute: Industrial demand and supply review for 2024 ↗
- LBMA: Silver Good Delivery refiners ↗
Explore the data and markets
Continue your research
All guides →
Carbon markets explained: allowances, credits and the integrity of climate claims
Distinguish compliance allowances from carbon credits, and examine baselines, additionality, durability, retirement and corporate accounting.
Electricity markets: prices, grids and the energy transition
A practical guide to dispatch, marginal prices, congestion, storage duration, capacity markets and the difference between wholesale power and retail bills.
Copper and Industrial Demand: Reading Construction, Grids, Supply and Inventories
How copper links industrial activity, electrification, mining and recycling—and why its price is an imperfect economic barometer.