
Stock Splits: Share Counts, Adjusted Prices and Economic Value
Understand forward and reverse splits, per-share comparisons, fractional settlements and why changing share units does not create business value.
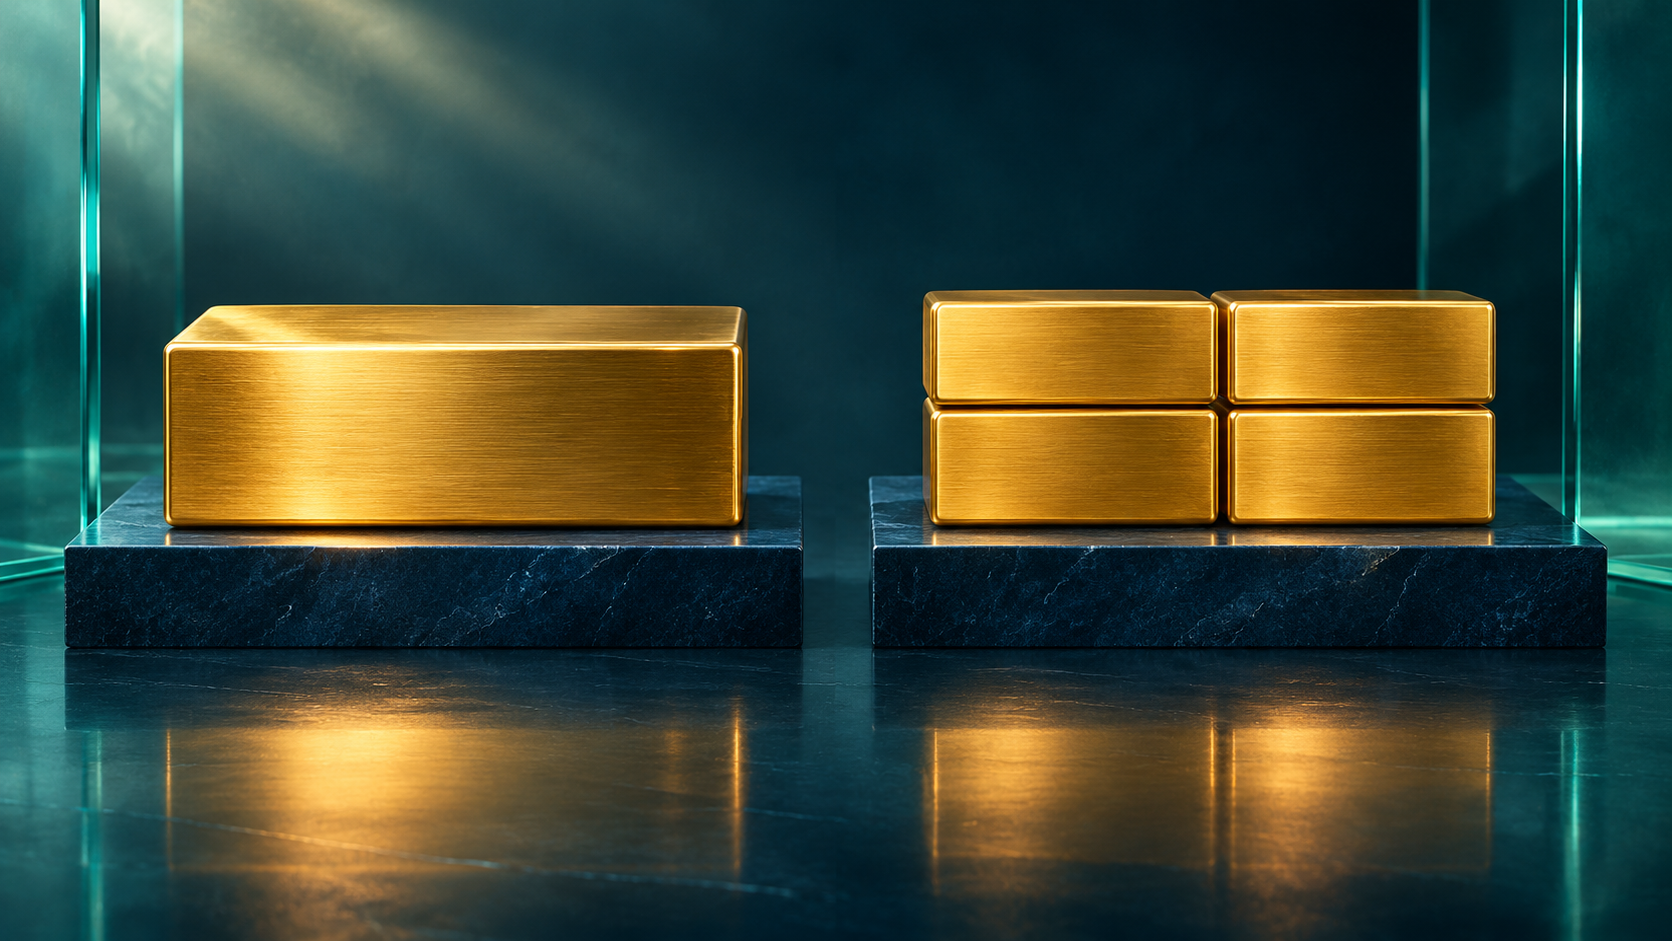
A share is a unit of ownership, not a fixed quantity of value
A stock split changes how a company's existing ownership is divided into quoted units. It does not, by itself, add a factory, improve a product, repay debt or bring cash into the business. This distinction is the starting point for understanding both forward and reverse splits. The same economic claim can be expressed through more inexpensive shares or fewer expensive shares. A shareholder should therefore connect the quoted price with the number of shares owned and the total shares outstanding. Looking only at the price confuses the size of the unit with the size of the investment. Corporate announcements can still influence market expectations, and trading conditions can change around implementation. Those possible effects are separate from the arithmetic of the split itself. All examples in this guide are hypothetical and isolate the corporate action from unrelated market movements, fees and other changes.
Forward splits multiply shares and divide the reference price
Suppose an investor holds 100 shares quoted at 60 dollars, giving a position worth 6,000 dollars. In a three-for-one split, the holding becomes 300 shares and the mechanically equivalent reference price becomes 20 dollars. Multiplying the new quantity by the new price still gives 6,000 dollars. If every outstanding share receives the same treatment, the investor's percentage ownership remains unchanged. The company has not gifted an additional economic stake merely because the account displays more units. Real trading prices need not remain exactly at the theoretical reference level after trading resumes because information and orders continue to arrive. That movement should be measured against the adjusted reference price, not against the old unadjusted quotation. A three-for-one split also means three shares in total for each former share, rather than three additional shares plus the original. Reading the ratio precisely avoids a surprisingly common calculation error.
Reverse splits consolidate units without repairing business losses
Now consider 250 shares at 2 dollars each, worth 500 dollars. A one-for-five reverse split consolidates the holding into 50 shares with a theoretical price of 10 dollars, again worth 500 dollars. The higher quotation does not reverse a previous economic loss. If the original investment cost 1,000 dollars, the corporate action alone does not restore that amount. Companies may pursue reverse splits for different reasons, including a desired trading price or exchange-related considerations, but the specific announcement is necessary to understand the actual purpose. A reverse split is not a universal forecast of future performance, just as a forward split is not proof of business strength. The useful question is what has changed in operations, financing and shareholder rights beyond the number of units. Any simultaneous capital raising, restructuring or change in rights must be analysed separately rather than attributed to the split ratio.
A split differs from issuing shares or buying them back
Share counts can change through transactions that have very different economics. A new issue may bring cash into the company and change existing shareholders' ownership percentages. A buyback uses company resources to retire or hold shares, with consequences that depend on price, funding and subsequent treatment. A proportional split simply changes the unit count without the same exchange of resources. Confusing these events makes statements such as more shares always means dilution unreliable. Ownership dilution requires examining who receives the shares and what the company receives in return. Authorised shares, issued shares, treasury shares and shares outstanding are also distinct categories. An announcement may alter more than one category, and legal capacity to issue shares does not prove that issuance has occurred. The analytical bridge should reconcile beginning and ending outstanding shares by event, rather than treating every change in the denominator as economically identical.
Adjusted histories prevent artificial price jumps
Historical charts need a consistent share unit. If a two-for-one split takes a quotation mechanically from 80 dollars to 40 dollars, an unadjusted chart displays a 50 percent fall even though the split itself caused no such loss. A split-adjusted history rescales earlier prices so that returns across the event are comparable. Data providers can also adjust volumes and may offer separate series for splits only or for splits and cash distributions. Those series should not be treated as interchangeable. A historical price shown today may therefore differ from the actual quotation recorded on that date. This is not necessarily an error; it can be a deliberate restatement of units. Before calculating returns or testing a rule, inspect the provider's adjustment policy and corporate-action factors. Mixing adjusted closing prices with unadjusted opening prices or share counts can manufacture results that never existed in an investor's account.
Cash distributions must use the matching share unit
A dividend per share can fall numerically after a split without reducing the aggregate cash attached to an unchanged holding. Suppose 100 shares each receive an annual distribution of 3 dollars, totalling 300 dollars. After a three-for-one split, a distribution of 1 dollar on each of 300 shares also totals 300 dollars. This is only an equivalence example, not a prediction that a board will maintain any payout. Actual declarations can change independently of the split and must be read directly. Dividend yield calculations likewise require a dividend and price expressed on the same unit basis and over a clearly identified period. Comparing an old per-share dividend with a new split-adjusted price creates an artificial yield increase. The broader discipline is to separate cash received, number of units and valuation changes, then reconcile them before interpreting a headline about dividend growth or shareholder returns.
Fractional entitlements depend on the actual terms
Not every holding divides neatly into a reverse-split ratio. A holder of 23 shares facing a one-for-five consolidation has a mathematical entitlement of 4.6 new shares. That arithmetic does not establish whether the account will retain a fraction, receive cash for a fraction or be treated through another permitted process. The issuer's terms, the ownership channel and the intermediary's handling matter. Fractional investing services are not necessarily identical to corporate-action fractional entitlements. Investors should distinguish the announcement date, relevant entitlement dates and the date trading begins on the new basis, using official notices rather than assuming one universal sequence. Cash received instead of a fraction also changes the remaining invested amount and can introduce transaction-specific consequences. This guide makes no jurisdiction-specific tax assumption. A complete reconciliation records new whole shares, any remaining fraction, cash settlement and charges rather than checking only the displayed share price.
Related contracts need their own corporate-action review
An equity holding and an option referencing that equity are different contracts. A split can require adjustments to an option's strike, deliverable, contract count or other terms, depending on the event and the relevant clearing framework. It is unsafe to assume that every reverse split leaves a standard contract representing the usual number of shares. The authoritative adjustment notice is more useful than a generic shortcut. Open orders and intermediary displays can also be handled differently around corporate actions, so an account view may temporarily combine information updated at different times. None of this means that a split creates an arbitrage merely because two screens look inconsistent. The underlying entitlement, settlement terms and timestamp need reconciliation first. This operational perspective matters for research as well as execution: a historical options dataset may contain adjusted contracts that cannot be compared directly with ordinary contracts bearing similar labels.
Separate mechanical neutrality from market interpretation
A useful split review begins with the ratio and a before-and-after reconciliation of shares, reference price and total position value. It then checks whether rights, resources or concurrent transactions have changed. Next come consistent earnings, dividend and historical-price units, followed by fractional treatment and any related-contract adjustments. Only after those checks should an analyst consider why management chose the action and whether accessibility, liquidity or market perceptions might change. Those effects are empirical questions, not guaranteed benefits embedded in the ratio. A lower nominal price does not automatically make a company cheaper relative to earnings, assets or cash generation. A higher nominal price after consolidation does not make a troubled balance sheet healthier. The economic assessment remains grounded in the business and its financing. The split tells readers how ownership is packaged; valuation asks what that ownership is worth and why.
Test a scenario. Explore the market.
Hypothetical inputs for learning. Change the assumptions to see the arithmetic; these are not current market values or forecasts.
Same period for both inputs. Before taxes and fees. Formula: (1 + return) ÷ (1 + inflation) − 1. Methodology ↗
Input limits: returns, inflation and currency changes −99% to 1,000%; duration 0–30; yield changes −200 to 200 basis points.
Open an interactive market chart
Market context, not a direct measure of every subject in this article. Provider data may be delayed or unavailable. Check the instrument, quote currency and timestamp.
Open the full market workspace →Sources & further reading
Primary institutional sources underpin this educational guide. Follow the links for the original definitions, methods and research. Hypothetical examples in the text are explanatory, not current quotes or forecasts.
- SEC: Stock Splits ↗
- Investor.gov: Stock Split ↗
- Investor.gov: Reverse Stock Splits ↗
- IFRS: IAS 33 Earnings per Share ↗
- Investor.gov: Fractional Share Investing ↗
- Nasdaq: Historic Stock Lookup ↗
- Nasdaq Data Link: Sharadar Equity Prices Documentation ↗
- Options Industry Council: Splits Happen ↗
- Options Industry Council: Corporate Action FAQs ↗
- NYSE: Corporate Actions ↗
- Nasdaq: Three-for-One Split and Quarterly Dividend Announcement ↗
Explore the data and markets
Continue your research
All guides →
Working Capital and the Cash Conversion Cycle: Where Operating Cash Gets Tied Up
Connect inventory, customer collections and supplier payments to cash flow, growth and liquidity without confusing a short cycle with a healthy business.
Mergers and Acquisitions: Reading the Economics Behind the Deal Value
Separate equity value, enterprise value, financing and synergies to understand who gains, who pays and what must happen after an acquisition closes.
IPOs, Primary and Secondary Markets: Where the Money and Ownership Go
Understand IPO proceeds, selling shareholders, allocation, dilution, public float and lockups before interpreting an offering headline.