
Oil refining: crack spreads, product markets and the cost of turning crude into fuel
How crude quality, product yields, operating costs and inventories shape refining economics, with a worked 3-2-1 example.
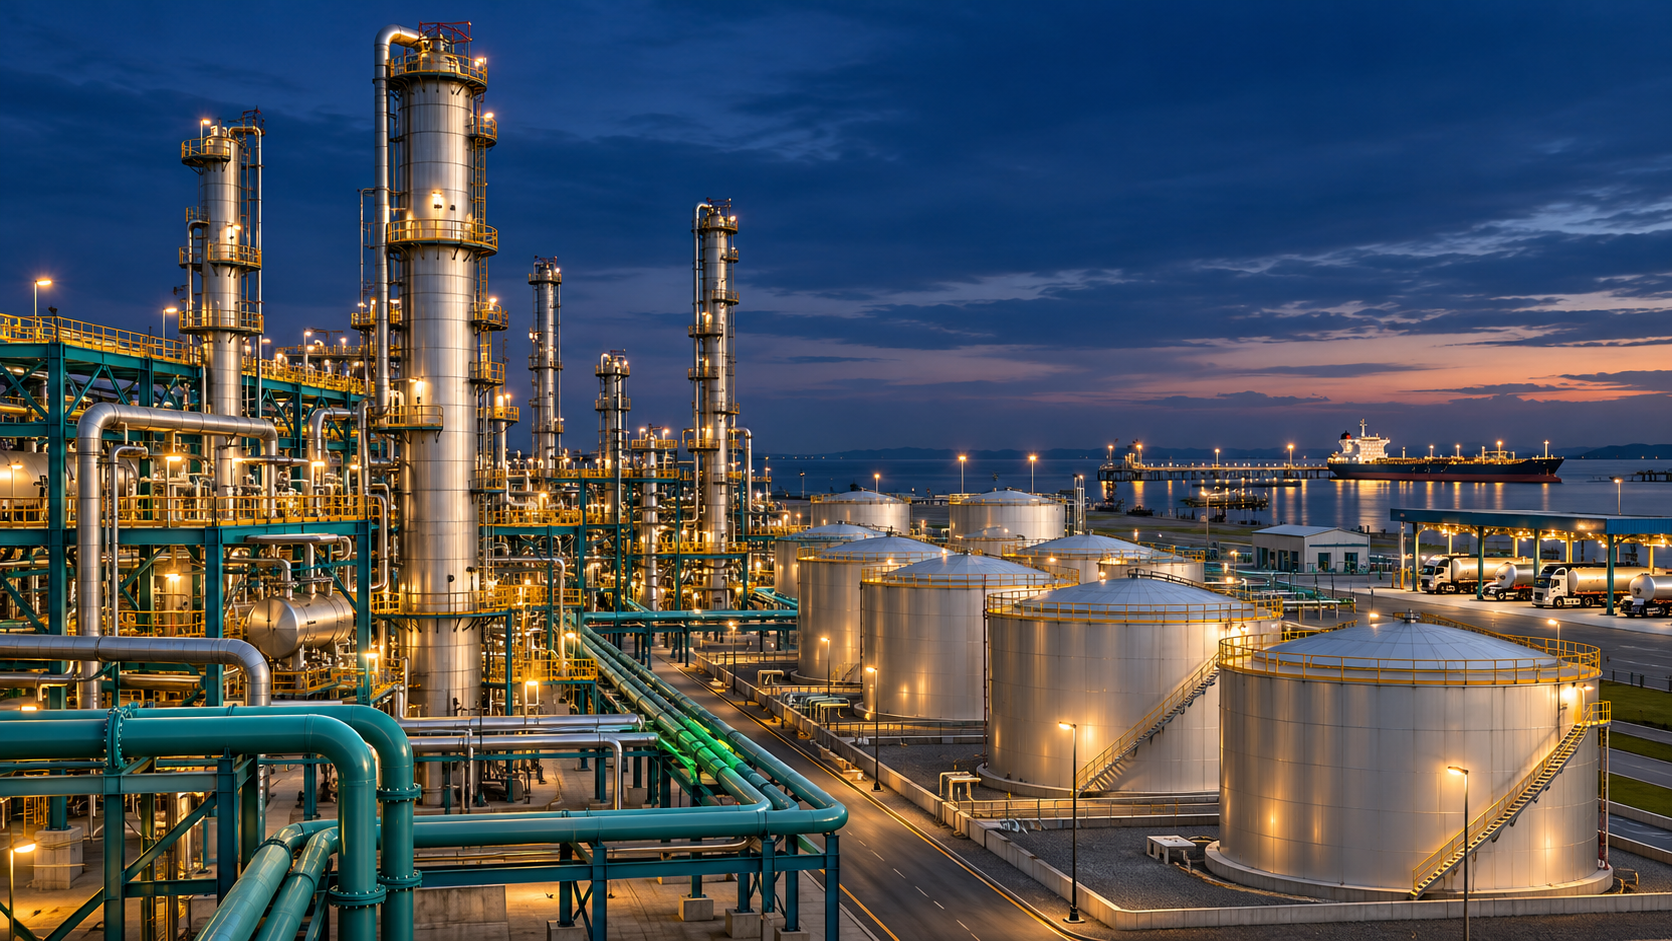
A refinery connects several markets
A refinery buys crude oil and other inputs, transforms them, and sells a basket of products into markets with different customers. Gasoline, diesel, jet fuel and other outputs do not share identical demand cycles. The business therefore cannot be understood from the crude price alone. A fall in crude can help input costs, but it offers little protection if product prices fall faster. Conversely, expensive crude can coexist with attractive refining economics when usable product supply is especially tight. The key relationship is the value of the output basket relative to the delivered input basket and operating costs. This guide explains that relationship using educational examples, not forecasts or trading recommendations. Treat crude production, refinery processing and final fuel consumption as connected stages with separate constraints, inventories and prices. A disturbance can benefit one stage while damaging another.
Crude quality changes the economic calculation
Crude grades differ in density, sulfur content and the mix of material that a particular refinery can turn into saleable products. A cheaper grade is not automatically the cheaper economic choice. Additional processing, energy needs, transport or a less valuable output mix may absorb its discount. Refinery configuration determines which inputs can be processed efficiently and how flexible the resulting product mix can be. Compare delivered crude costs rather than a headline benchmark that may refer to another location or quality. The relevant comparison also changes with product prices: a configuration suited to strong diesel demand may face different economics when gasoline is comparatively more valuable. This is a matching problem between feedstock, equipment and customer demand. It is not a universal ranking in which one grade or one refinery type always wins.
Barrels measure volume, not identical output
An oil barrel contains 42 US gallons. That conversion matters when crude is quoted per barrel and products per gallon; an imperial gallon is a different unit. Refinery output volume can exceed crude input volume because lighter products occupy more space, with additional inputs and statistical definitions also relevant. This processing gain is not the creation of mass or free economic value. Product yields describe the share of particular outputs under a stated accounting basis, and reported definitions can include adjustments for blending components or unfinished oils. Actual refineries produce more than just gasoline and diesel. A simple benchmark basket is therefore an analytical approximation, not a physical recipe. Before comparing two yield charts, check input coverage, net versus gross production, volume versus mass and the time period. Otherwise apparent efficiency differences may merely reflect incompatible measurement.
A hypothetical 3-2-1 spread in consistent units
The 3-2-1 approximation compares three barrels of crude with two barrels of gasoline and one barrel of distillate. Consider hypothetical prices, not market observations: crude costs 80 dollars per barrel, gasoline 2.40 dollars per US gallon and distillate 2.70 dollars per US gallon. Multiplying by 42 gives product values of 100.80 and 113.40 dollars per barrel. The basket difference is twice 100.80 plus 113.40 minus three times 80, which equals 75 dollars for the three-barrel input basket. Dividing by three gives 25 dollars per input barrel. Omitting the final division exaggerates the per-barrel measure threefold. This is a gross product-versus-crude price difference. It does not establish the actual yield, delivered acquisition cost or net profit of any refinery. Locations, dates and product specifications must also match before the calculation becomes a meaningful comparison.
A crack spread is not net profit
The benchmark calculation leaves out important costs and revenues. Energy, purchased hydrogen, labor, maintenance, insurance, freight and environmental compliance can materially change the result. Depreciation, financing and taxes matter when moving from an operating contribution to net earnings. Actual product mix includes outputs not represented in the simple basket, while discounts and premiums change realized selling prices. Even a correctly calculated spread cannot be multiplied mechanically by nameplate capacity to forecast profit: utilization, downtime, input quality and accounting inventory effects intervene. A useful analytical bridge starts with benchmark gross value, adjusts for location and yield, then deducts relevant operating costs before considering corporate expenses and capital charges. Keep these stages separate. Calling every change in a quoted spread a corresponding change in shareholder earnings hides the assumptions that most need examination.
Products have different demand calendars
Gasoline demand can respond to driving patterns, diesel to freight and industry, and jet fuel to aviation activity. Heating uses also connect some distillate markets to weather. Seasonal fuel specifications and the timing of maintenance can affect supply alongside consumption. These relationships vary by region, so a pattern observed in one country is not a global law. A strong product spread can reflect seasonal buying, an unexpected outage or restricted imports rather than durable growth in final demand. Compare the same season across years and inspect several products together. If gasoline strengthens while diesel weakens, a single average margin conceals an important change in the output basket. Retail pump prices add distribution, marketing and taxes, meaning they should not be substituted directly for wholesale product prices when estimating a refinery benchmark.
An outage can separate crude and product prices
When a refinery reduces throughput, it may buy less crude while supplying fewer finished products. Other conditions unchanged, that combination can weaken local crude demand and tighten local product availability simultaneously. The resulting spread may widen even though the affected refinery earns less because it sells fewer barrels and incurs repair costs. This distinction between market opportunity and an individual operator's ability to capture it is essential. Planned maintenance differs from an unexpected disruption in how much preparation buyers and suppliers can make. Spare capacity elsewhere matters only if the necessary products can reach the affected market in time and meet its specifications. Analyze the duration, affected processing capability and logistical alternatives rather than treating every announced outage as the same shock. Restart dates are expectations until operations actually recover.
Inventory matters where customers can use it
A national inventory total combines locations, ownership and product grades that may not be immediately interchangeable. Stocks near a consuming region can have a different practical value from barrels separated by a constrained pipeline or long sea voyage. A product also needs the right specification, storage access and delivery schedule. Inventory builds do not always signal weak consumption: imports, refinery output changes and deliberate seasonal preparation can all contribute. Likewise, a draw may reflect temporary logistics rather than lasting shortage. Examine changes alongside throughput, trade and estimated demand, preferably over more than one weekly observation. For economic interpretation, distinguish physical availability from an accounting valuation gain. The same stored barrels can rise in reported value without increasing the quantity available to customers or improving the refinery's underlying operating efficiency.
Benchmark spreads have basis and timing risk
Exchange contracts and published spot assessments describe specified products, locations and delivery periods. A refinery's purchases and sales may differ from every one of those definitions. The difference between a physical price and its chosen benchmark is basis risk; timing mismatches introduce another source of variation. A futures spread is therefore not a guaranteed realized refinery margin. Contract sizes must also be converted consistently, and a comparison between different delivery months can incorporate storage and seasonal expectations. Educational calculations are most useful when all assumptions are written beside the result. State the crude benchmark, product grades, locations, dates, units and basket weights. Then explain which costs are excluded. This discipline makes comparisons reproducible and prevents a visually impressive chart from implying precision that the underlying proxy does not possess.
Read the chain before drawing a conclusion
A practical refining review begins with the question being asked: wholesale fuel inflation, crude demand, regional supply security or corporate earnings. Each requires a different boundary. For product availability, follow refinery runs, relevant outages, inventories and trade. For operating economics, add delivered crude quality, realized product mix and costs. For final consumer prices, examine distribution and taxes separately. Label observed facts, estimates and scenarios so that an assumed restart or demand recovery does not quietly become a confirmed event. Compare alternatives: a wider spread caused by stronger consumption differs from one caused by lost capacity. Finally, preserve the unit checks from the numerical example. A sound interpretation connects physical barrels, market prices and financial costs without collapsing them into one number. That connection is more informative than a confident directional claim about oil alone.
Test a scenario. Explore the market.
Hypothetical inputs for learning. Change the assumptions to see the arithmetic; these are not current market values or forecasts.
Same period for both inputs. Before taxes and fees. Formula: (1 + return) ÷ (1 + inflation) − 1. Methodology ↗
Input limits: returns, inflation and currency changes −99% to 1,000%; duration 0–30; yield changes −200 to 200 basis points.
Open an interactive market chart
Market context, not a direct measure of every subject in this article. Provider data may be delayed or unavailable. Check the instrument, quote currency and timestamp.
Open the full market workspace →Sources & further reading
Primary institutional sources underpin this educational guide. Follow the links for the original definitions, methods and research. Hypothetical examples in the text are explanatory, not current quotes or forecasts.
- EIA: Refining inputs and outputs ↗
- CME Group: An introduction to crack spreads ↗
- EIA: 3:2:1 crack spread ↗
- EIA: Refinery yield definition ↗
- EIA: Factors affecting diesel prices ↗
- EIA: Gasoline price fluctuations ↗
- EIA: Petroleum product production ↗
- EIA: Petroleum product balance ↗
Explore the data and markets
Continue your research
All guides →
Critical minerals recycling: collection, recovery and the economics of circular supply
Why installed metal is not immediately available scrap, and how collection, quality, recovery and commercial terms determine secondary supply.
Uranium Markets: Fuel-Cycle Services, Contracts and Security of Supply
Separate uranium material from civilian fuel-cycle services, then examine procurement schedules, inventory coverage and the economics of supply delays.
Lithium Economics: Chemical Grades, Battery Demand and Supply-Chain Bottlenecks
Follow lithium from deposits to qualified battery chemicals, examining benchmarks, project timing, inventory cycles, substitution and recycling.