
Uranium Markets: Fuel-Cycle Services, Contracts and Security of Supply
Separate uranium material from civilian fuel-cycle services, then examine procurement schedules, inventory coverage and the economics of supply delays.
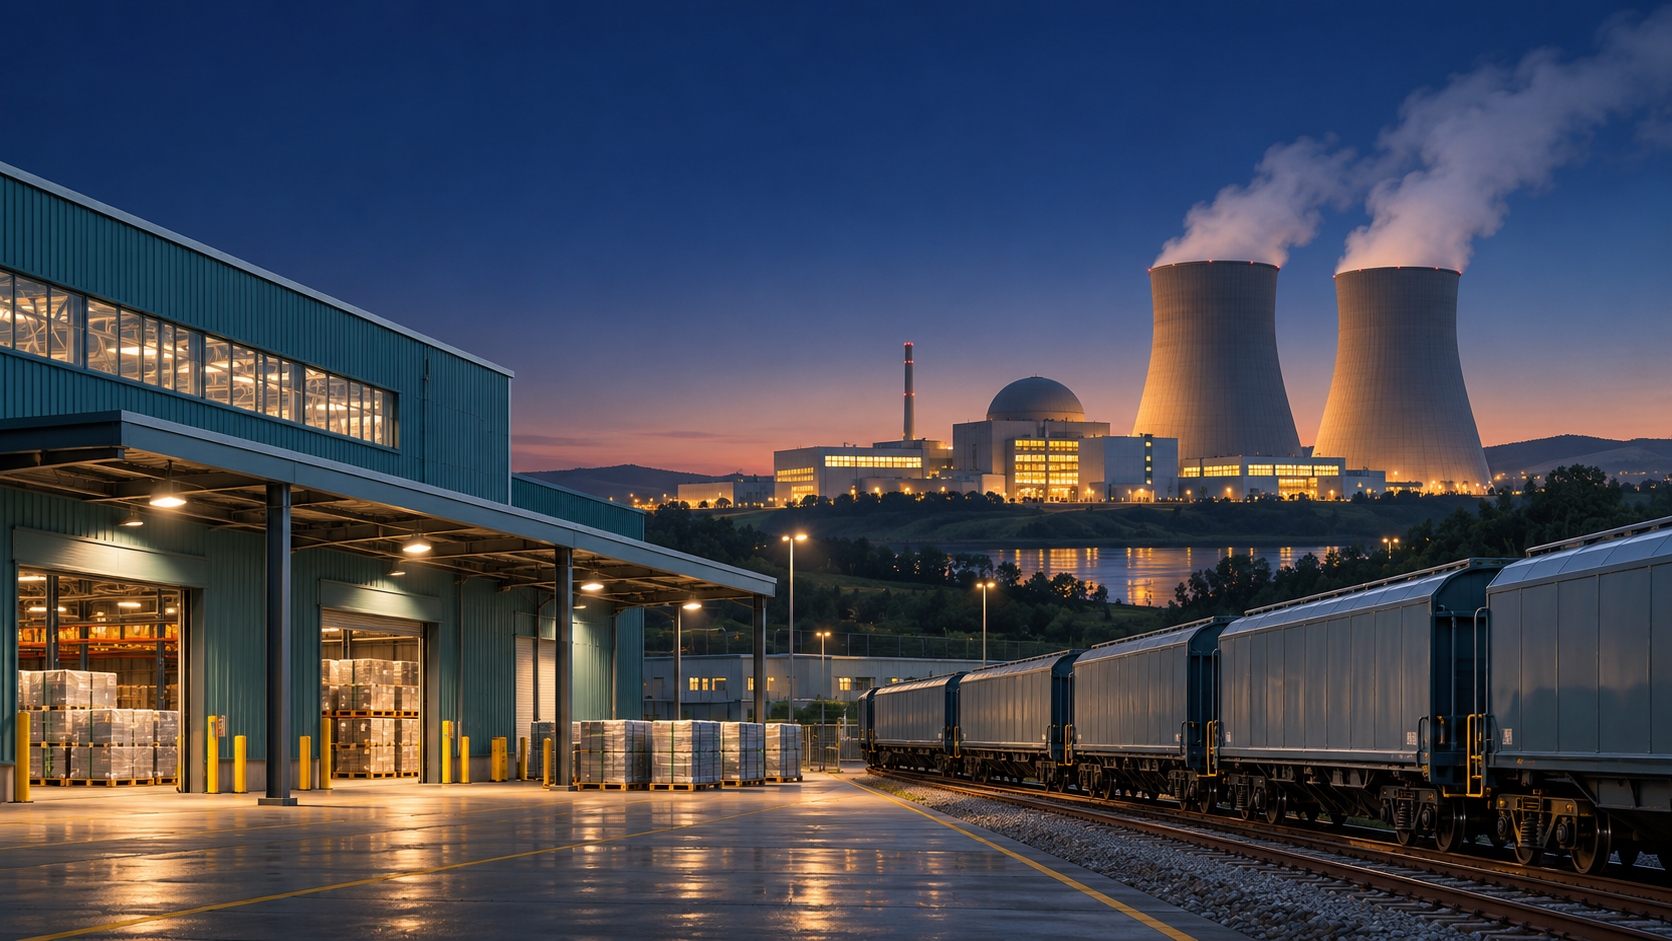
A uranium purchase is not a complete fuel supply
Civil nuclear fuel markets combine a mineral commodity with specialized industrial services and long-term procurement. Mining supplies uranium material, but a power operator also needs the appropriate conversion, enrichment where required, fabrication, transport and regulatory arrangements before fuel is usable in its reactor. Different reactor designs have different requirements, so the chain is not identical everywhere. A shortage of one service can matter even when uranium resources are abundant. This is why a uranium price chart cannot describe the entire economics of nuclear fuel supply. The useful starting point is to separate material availability from service capacity, qualification and delivery timing. This guide discusses civilian market structure and procurement at a high level; it does not provide operational nuclear instructions or recommend a commodity, producer share or investment strategy.
Resources need investment before becoming deliveries
Geological resources describe material identified under specified assumptions, not an immediately available annual flow. Mine development requires financing, approvals, infrastructure, workforce and successful operation. Expanding an existing site, restarting an idled operation and building a new project have different timelines and risks. A favorable commodity price can improve project economics without making production appear in the next quarter. Conversely, prolonged weak prices can defer investment and reduce the future supply pipeline. Resource and reserve classifications, cost categories and reporting dates must be read before comparing headline numbers. The NEA and IAEA's resource assessments are useful for long-term context, but they should not be interpreted as short-term delivery schedules. A credible supply forecast separates existing output, committed expansions and more uncertain proposals, rather than treating every announced project as equally likely to produce on time.
Conversion and enrichment are separate service markets
For many commercial reactor supply chains, conversion and enrichment are distinct purchased services rather than synonyms for uranium mining. Their capacity, contracts and industrial concentration can differ from the mineral market. A utility may hold sufficient uranium material yet need access to the relevant service at the required time. Service prices can therefore move differently from the uranium component. Procurement analysis should identify which party supplies each input, where the service is performed and what contractual flexibility exists if a supplier is unavailable. This is a commercial mapping exercise, not a description of how to conduct the processes. Do not combine quantities measured as uranium material with service units without a documented accounting basis. A reported increase in total fuel spending may reflect higher service charges, altered delivery timing or a different contract mix rather than a matching increase in the mineral price.
Fabrication and qualification link supply to a reactor
Fuel fabrication is a specialized industrial stage that produces a qualified product for a particular reactor context. It is not simply the purchase of a generic commodity from any available seller. Supplier acceptance, technical compatibility, quality assurance and regulatory review can influence the time needed to establish an alternative source. This means diversification must be planned before a disruption, not assumed to occur instantly after one. Capacity announcements should be distinguished from licensed, qualified and commercially available supply. A facility may be under construction or expansion while customers still await accepted delivery capability. The economic question is whether the complete supply chain can meet an operator's schedule, not whether a single stage has spare capacity. High-level regulator descriptions help explain the institutional constraints, while specific approvals require checking the applicable jurisdiction and date.
Spot indicators and delivered contract prices answer different questions
Uranium procurement includes spot transactions and longer-term agreements, with price mechanisms and delivery schedules that vary. A spot indicator reflects a particular segment of activity, while an annual average price paid by utilities can include deliveries under contracts negotiated years earlier. The two series need not move together. Agreements may incorporate fixed components, market references, escalation or other terms; public averages do not reveal every contract's economics. Read whether a statistic measures contracts signed, material delivered or future commitments. EIA distinguishes uranium-component prices from conversion and enrichment services in relevant tables, an important warning against comparing unlike figures. A higher average delivered price can arise from a changing contract mix even if a current spot quotation is unchanged. The correct comparison preserves units, material basis, delivery period and the inclusion or exclusion of services.
Procurement coverage is a schedule rather than one percentage
Utilities plan fuel procurement against future operational requirements. Contracted deliveries, inventory and remaining uncovered needs must be aligned by year and by stage of the supply chain. In a hypothetical commercial example, an operator expects a material requirement of 100 units in a future period, has 60 units of scheduled contract deliveries and allocates 25 units of existing usable inventory. The remaining requirement is 15 units, assuming all quantities are comparable and deliveries occur as planned. That calculation says nothing about whether conversion, enrichment or fabrication slots are secured. Nor does a maximum contractual delivery amount necessarily equal a firm minimum entitlement. Review optional quantities and timing provisions separately. A single aggregate coverage ratio can conceal a near-term gap or excessive dependence on one supplier, making the year-by-year schedule more informative than a headline total.
Inventory value depends on form, location and availability
Inventory can provide a buffer against disruption, but not every reported holding is equally useful for an upcoming delivery requirement. Material form, ownership, location, contractual commitments and access to subsequent services matter. A global inventory estimate is not the same as material freely available for sale. Some holdings are strategic, allocated to future operations or already embedded in the production chain. Secondary supply and inventory movements can affect the balance between mine output and reactor-related requirements, so those two annual flows need not match exactly. Avoid interpreting every difference as an immediate shortage or surplus. Stock data also have reporting boundaries and revisions. The practical question is which inventory can bridge which obligation, under what conditions and with what lead time. That is more precise than treating all stored material as a single liquid pool.
Reactor demand and project announcements operate on different clocks
Existing reactor operations, planned outages, lifetime extensions, closures and new construction influence fuel requirements. An announced project is not equivalent to an operating reactor, and its procurement profile can differ from routine replacement needs at an established plant. Forecasts therefore depend on commissioning schedules and policy or commercial decisions that can change. A broad rise in interest in nuclear power may support long-term expectations without translating into immediate fuel purchases of the same scale. Conversely, procurement ahead of future operation can move market demand before electricity generation begins. Separate physical consumption from purchasing and inventory building. Long-term scenarios should state their assumptions about capacity and timing rather than present one path as inevitable. The distinction is essential when interpreting a short-term uranium price move as evidence about decades of future nuclear deployment.
Fuel-price changes do not map one-for-one into electricity cost
Nuclear generation economics include capital, operations, maintenance and other obligations as well as fuel. Within fuel spending, uranium material is only one component. In a deliberately hypothetical budget, suppose total generation cost is 100 units, fuel accounts for 20 and the uranium component accounts for eight of that total. A 50 percent increase in uranium cost adds four units if quantities and all other costs remain unchanged, lifting the total to 104 rather than 150. Actual shares and timing differ across plants and contracts; the example is not an industry benchmark. Procurement lags can delay pass-through, while disruptions to service availability may matter beyond their direct price share. Separate price sensitivity from operational continuity. A relatively small cost component can still be critical if its absence prevents a scheduled supply chain from functioning.
Read material, services and delivery risk together
Begin with the reactor market and procurement horizon, then map material needs and each service stage separately. Compare actual mine output with credible project milestones, and distinguish resource adequacy from delivery readiness. Read contract prices according to signing and delivery dates, preserving the scope of included services. Reconcile inventory and contractual coverage by period, noting optional volumes and supplier concentration. Examine whether diversification is qualified and operational rather than merely announced. Use hypothetical budgets to clarify sensitivity without turning them into forecasts. EIA, Euratom, NEA, IAEA and national regulator publications offer different views of the same civilian supply network. A sound conclusion identifies the constrained stage, the exposed delivery window and the evidence needed to resolve uncertainty. This framework explains why mineral price, fuel-service price and security of supply can tell different stories at the same time.
Test a scenario. Explore the market.
Hypothetical inputs for learning. Change the assumptions to see the arithmetic; these are not current market values or forecasts.
Same period for both inputs. Before taxes and fees. Formula: (1 + return) ÷ (1 + inflation) − 1. Methodology ↗
Input limits: returns, inflation and currency changes −99% to 1,000%; duration 0–30; yield changes −200 to 200 basis points.
Open an interactive market chart
Market context, not a direct measure of every subject in this article. Provider data may be delayed or unavailable. Check the instrument, quote currency and timestamp.
Open the full market workspace →Sources & further reading
Primary institutional sources underpin this educational guide. Follow the links for the original definitions, methods and research. Hypothetical examples in the text are explanatory, not current quotes or forecasts.
- EIA: Uranium Marketing Annual Report ↗
- EIA: Uranium Component Prices and Services ↗
- EIA: Future Contracted Deliveries ↗
- EIA: Uranium Inventories ↗
- NRC: Stages of the Nuclear Fuel Cycle ↗
- NRC: Fuel Cycle Facility Licensing ↗
- NEA and IAEA: Uranium 2024 Resources, Production and Demand ↗
- Euratom Supply Agency: Market Publications ↗
- US Department of Energy: Nuclear Fuel Cycle ↗
- Euratom: Annual Report 2024 ↗
Explore the data and markets
Continue your research
All guides →
Oil refining: crack spreads, product markets and the cost of turning crude into fuel
How crude quality, product yields, operating costs and inventories shape refining economics, with a worked 3-2-1 example.
Critical minerals recycling: collection, recovery and the economics of circular supply
Why installed metal is not immediately available scrap, and how collection, quality, recovery and commercial terms determine secondary supply.
Lithium Economics: Chemical Grades, Battery Demand and Supply-Chain Bottlenecks
Follow lithium from deposits to qualified battery chemicals, examining benchmarks, project timing, inventory cycles, substitution and recycling.