
Brent vs WTI: Understanding the Global Oil Benchmarks
A practical explanation of oil quality, delivery locations, benchmark spreads and futures curves, with the physical market kept in view.
A benchmark is a reference, not all oil
Brent and West Texas Intermediate, usually called WTI, are reference points for pricing crude oil. They are not interchangeable names for a single universal barrel. Crude differs in quality, delivery location, transport access and timing. A benchmark gives buyers and sellers a common starting point; the actual commercial price can include a premium or discount reflecting the specific cargo and contract.
This distinction explains why two headlines can report different oil prices without either being wrong. One may refer to a nearby futures contract, another to a physical assessment, and a third to a different delivery month. Before comparing numbers, identify the instrument, timestamp, currency, unit and settlement basis. A price without these details is incomplete information. The same discipline is necessary when comparing an oil chart with inflation, company earnings or government revenue.
Quality matters, but location can matter more
Two important crude characteristics are density and sulfur content. Light and sweet describe relatively low density and low sulfur, respectively. These features affect processing requirements and the mix of products a refinery can obtain. They do not create a universal ranking of commercial value independent of circumstances. A refinery's equipment, operating limits and desired products influence what it is willing to pay for a particular crude.
Location adds another layer. A barrel available near an export terminal is economically different from a similar barrel behind a constrained pipeline. Transport, storage, insurance and scheduling consume money and time. The benchmark spread therefore cannot be explained solely by saying one crude is better. A comparison that ignores the route from producer to refinery omits much of the physical system that turns an abstract price into an executable transaction.
WTI and the importance of Cushing
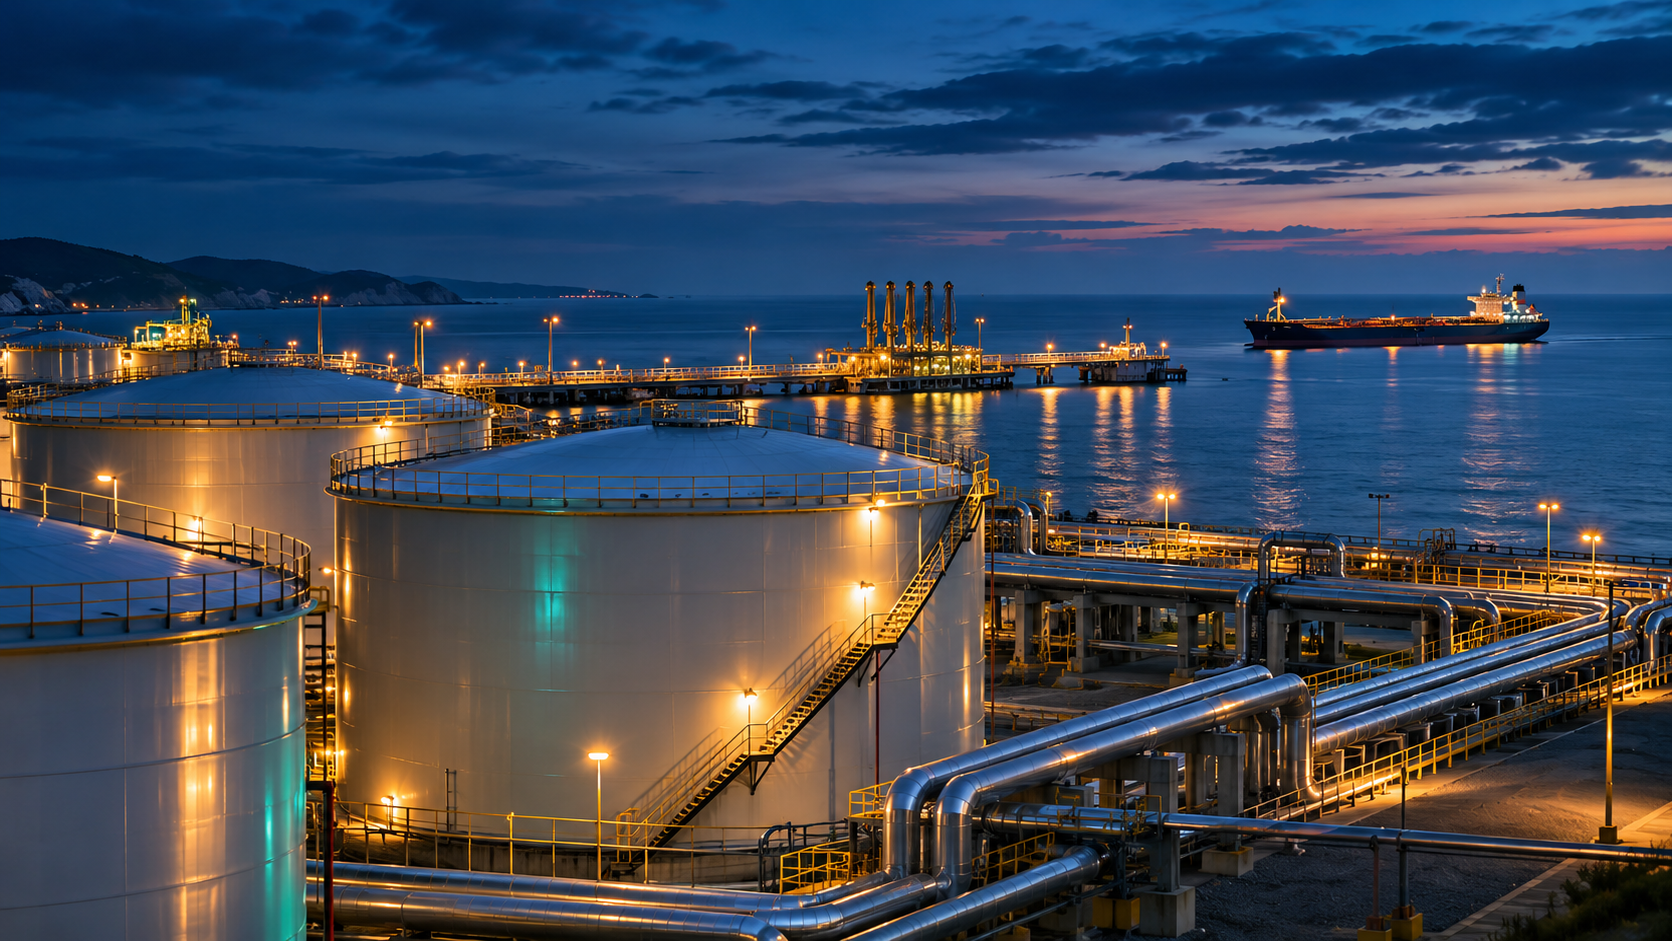
The NYMEX light sweet crude oil futures contract is physically deliverable at Cushing, Oklahoma, under exchange specifications. Cushing is a connected storage and pipeline hub, not simply a name attached to a screen price. Its infrastructure matters because delivery obligations must be met in the specified place and period. An expiring contract is therefore linked to the practical availability of qualifying crude and capacity there.
That does not mean WTI is economically isolated inside the United States. Pipelines, refining demand and export connections link inland supply with the Gulf Coast and international markets. Yet those connections have finite capacity and operating constraints. When local conditions change, the delivery-point economics may change faster than the global supply narrative. Reading storage and transport information alongside the contract specification helps explain movements that a worldwide demand headline alone cannot resolve.
Brent is a pricing ecosystem
Brent connects several related markets, including physical assessments, forward trading and exchange-traded futures. These references interact but are not identical. Dated Brent, for example, should not be casually substituted for the nearest ICE futures quote in a calculation. Each reference has a methodology and timing convention that must be understood before it is used to price a cargo or explain a reported spread.
ICE describes its Brent futures contract as deliverable through an exchange-for-physical mechanism, with an option to cash settle against the ICE Brent Index. Reducing this structure to the statement that Brent has no physical connection is misleading. Equally, describing every Brent-linked transaction as the delivery of one unchanged North Sea grade oversimplifies the benchmark's framework. Readers should consult the relevant specification and methodology, especially when historical comparisons span changes in the underlying pricing system.
What the Brent–WTI spread can reveal
Define the spread before interpreting it: Brent minus WTI is positive when the selected Brent price exceeds the selected WTI price. Match delivery months and observation times wherever possible. Otherwise, part of the apparent spread may simply be a calendar difference or a change that occurred between two observations. A chart should state the exact series, not only the names of the benchmarks.
The spread can reflect transport economics, regional inventories, refinery demand, export conditions and differences in the contracts themselves. Historical EIA analysis of bottlenecks illustrates why inland and seaborne benchmarks can diverge. Arbitrage provides a connecting mechanism, but it is not frictionless or instantaneous. Moving crude requires access to infrastructure and an economically feasible route. A wide spread is therefore a prompt to investigate constraints, not automatic evidence of a free profit that anyone can collect.
The futures curve answers a different question
A benchmark spread compares different references. A futures curve compares delivery dates for a given contract family. When nearby prices exceed later prices, the curve is called backwardated. When later prices exceed nearby prices, it is in contango. These shapes can provide information about the value of immediate availability, storage economics and the balance of hedging demand, but they are not direct predictions of future spot prices.
A hypothetical market can have Brent above WTI while both curves are backwardated, or Brent above WTI while one curve is in contango. There is no contradiction: location and timing are different dimensions. For a futures-based investment product, rolling from an expiring contract to another also affects performance. A rising headline spot price does not guarantee an identical return from every oil-linked instrument. Product structure, fees and the sequence of contract prices matter.
Read shocks through the physical system
Imagine an unplanned pipeline restriction near an inland hub. Local supply may become harder to move even though worldwide consumption is unchanged. The regional price response can differ from the seaborne response. Now imagine an interruption to a shipping route. Freight, insurance, journey times and access to substitute cargoes may become more important than the latest inventory figure at a single inland location.
A third scenario is weaker refinery demand during maintenance. Crude demand can soften locally even if demand for finished fuel has not collapsed. These examples are hypothetical and deliberately separate mechanisms that headlines often combine. The analytical task is to follow the affected barrel: where it is produced, where it can go, when it can arrive and which facility can process it. The size and persistence of any price move require evidence beyond the scenario itself.
A disciplined oil-market reading list
Begin with contract specifications and the data provider's definition. Then compare equivalent months, inspect the futures curves and separate global balances from regional logistics. Inventory releases deserve context: distinguish crude from products, national totals from delivery-point stocks, and a weekly change from a seasonal pattern. Refinery utilization and import or export timing can help explain movements that a single headline number obscures.
When connecting oil to consumer inflation, remember that crude is an input rather than the final retail bill. Refining margins, distribution, taxes and exchange rates intervene. When connecting oil to an individual company, production mix, costs and contractual exposures intervene again. Brent and WTI are powerful organizing references because they make comparison possible. Their value increases when readers retain the physical details behind them, disclose uncertainty and resist turning one price or one spread into a complete explanation of the energy economy.
Sources & further reading
Primary institutional sources underpin this educational guide. Follow the links for the original definitions, methods and research. Hypothetical examples in the text are explanatory, not current quotes or forecasts.
- ICE: Brent Crude Futures ↗
- CME Group: Why Cushing Matters ↗
- CME Group: WTI physically delivered futures FAQ ↗
- EIA: North American benchmarks and bottlenecks ↗
- ICE: Evolution of Brent and its markets ↗
- CME Group: WTI export connections ↗
- EIA: Oil futures curve and market structure ↗
- Government of Alberta: Oil prices and value ↗
Explore the data and markets
Continue your research
All guides →
Copper and Industrial Demand: Reading Construction, Grids, Supply and Inventories
How copper links industrial activity, electrification, mining and recycling—and why its price is an imperfect economic barometer.
Agriculture and Food Price Shocks: From Harvests and Fertilizer to Household Costs
Trace how weather, stocks, energy, trade and currencies shape agricultural markets—and why supermarket prices respond differently.
Natural Gas Markets: Why Geography, LNG and Storage Shape Regional Prices
Understand the infrastructure, contracts and seasonal forces linking gas markets without turning them into a single uniform price.